

The first R550,000 of your retrenchment payout is tax free. Most retrenched employees never find this out until their payslip lands and the number looks smaller than they expected. A tax directive for retrenchment is the document that determines exactly how much SARS takes from your severance package before it reaches your bank account, and getting it wrong (or letting your employer skip it) can cost you thousands of Rands in overpaid tax that takes months to claim back.
This article explains exactly how the directive works, who applies for it, what the tax free threshold means in practice, and where employers and employees most commonly go wrong. If you have just been told your position is being cut, or if you are trying to work out what your final payout will actually look like after tax, this is the part of the process that decides your real take-home number.
What a Tax Directive for Retrenchment Actually Is
A tax directive is an instruction from SARS to your employer telling them exactly how much tax to deduct from a lump sum payment, in this case your retrenchment package. Without a directive, your employer has no legal authority to apply the special retrenchment tax tables, and payroll software will often default to taxing the whole amount as if it were normal monthly income. That mistake alone can push you into a far higher tax bracket than you should be in for that month, even though SARS refunds the difference eventually through your annual tax return.
Your employer applies for the tax directive on your behalf through SARS eFiling using a form called the IRP3(a), which covers severance benefits specifically. They submit your service history, your final remuneration details, and the reason for termination. SARS processes most retrenchment directives within a few working days, though this can stretch longer during peak periods around the end of the tax year in February and March.
How SARS Taxes Your Severance Package
South African tax law treats retrenchment lump sums more generously than ordinary income, and this is where the tax directive for retrenchment does its real work. The Income Tax Act sets a lifetime tax free threshold that currently sits at R550,000 for retirement fund lump sums and severance benefits combined. This is not R550,000 every time you get retrenched. It is a lifetime cumulative amount, so if you already withdrew a portion of a retirement fund lump sum in the past, that amount counts against the same threshold.
Above the tax free portion, SARS applies a sliding scale. The next tranche up to R770,000 is taxed at 18 percent, the tranche from R770,001 to R1,155,000 is taxed at 27 percent, and anything above R1,155,000 is taxed at 36 percent. These bands apply cumulatively across your lifetime lump sum withdrawals, not just the current payout, which is why your tax directive for retrenchment needs to account for any previous lump sums you have taken from a pension, provident, or retirement annuity fund.
Here is a practical example. Say your severance package comes to R650,000 and this is the first lump sum you have ever received. The first R550,000 falls into the tax free bracket. The remaining R100,000 gets taxed at 18 percent, which comes to R18,000. Your net severance after tax works out to R632,000.
Now take a second example where the numbers are bigger. Say you receive a severance package of R1,200,000 and you have never taken a lump sum before. The first R550,000 is tax free. The next R220,000 (up to R770,000) is taxed at 18 percent, coming to R39,600. The next R385,000 (up to R1,155,000) is taxed at 27 percent, coming to R103,950. The final R45,000 above R1,155,000 is taxed at 36 percent, coming to R16,200. Total tax comes to R159,750, leaving you with R1,040,250 net.
Severance Pay vs Notice Pay vs Retirement Fund Lump Sum: How Tax Differs
Employees frequently assume their entire final payout gets the same generous tax treatment. It does not. Each component is taxed differently, and only the severance portion qualifies for the retrenchment lump sum tables under a tax directive.
| Payment Type | What It Covers | How SARS Taxes It | ||
| Severance Pay | Statutory or negotiated retrenchment compensation | Retrenchment lump sum tax tables via tax directive, R550,000 tax free threshold applies | ||
| Notice Pay | Payment in lieu of working your notice period | Taxed as normal income at your standard PAYE rate | ||
| Leave Pay | Accrued annual leave paid out | Taxed as normal income at your standard PAYE rate | ||
| Retirement Fund Lump Sum | Withdrawal from pension, provident, or retirement annuity fund | Same lump sum tax tables as severance pay, shares the same lifetime R550,000 threshold |
This table matters because your total payslip on your last day might show four separate lines, and only one of them gets the tax break. Do not assume your whole final payment is tax free just because your severance component was.
The Common Mistake: Assuming Your Employer Handled the Directive Automatically
A common situation is an employee assuming that because their employer processed the retrenchment, the correct tax directive for retrenchment was automatically requested and applied. This is not always true, particularly at smaller businesses without a dedicated payroll or HR department. Many workers make the mistake of only checking their payslip number without ever confirming whether SARS actually issued a directive number for that specific payment.
If your employer taxes your full severance package as ordinary income because they never applied for the directive, you overpay tax that month, sometimes significantly. You can claim this back, but only when you submit your annual tax return, which means waiting months for money that should have been in your account immediately. Ask your employer directly for the SARS directive number applied to your payout before you sign off on your final payslip. If they cannot produce one, push them to apply before processing your final payment, not after.
Applying for Your Own Tax Directive If Your Employer Won’t
In most cases your employer must submit the directive application, since they are the one deducting the tax and paying it over to SARS through PAYE. But if your employer refuses, delays unreasonably, or has since closed down, you can escalate the matter through SARS directly, or seek help through the Department of Employment and Labour if the retrenchment itself is being disputed. Keep every document related to your termination and final payslip, since you will need your service certificate, your employment contract, and confirmation of your final remuneration if you end up applying for correction through your tax return instead.
What Happens to Your Retirement Savings Under the Two-Pot System
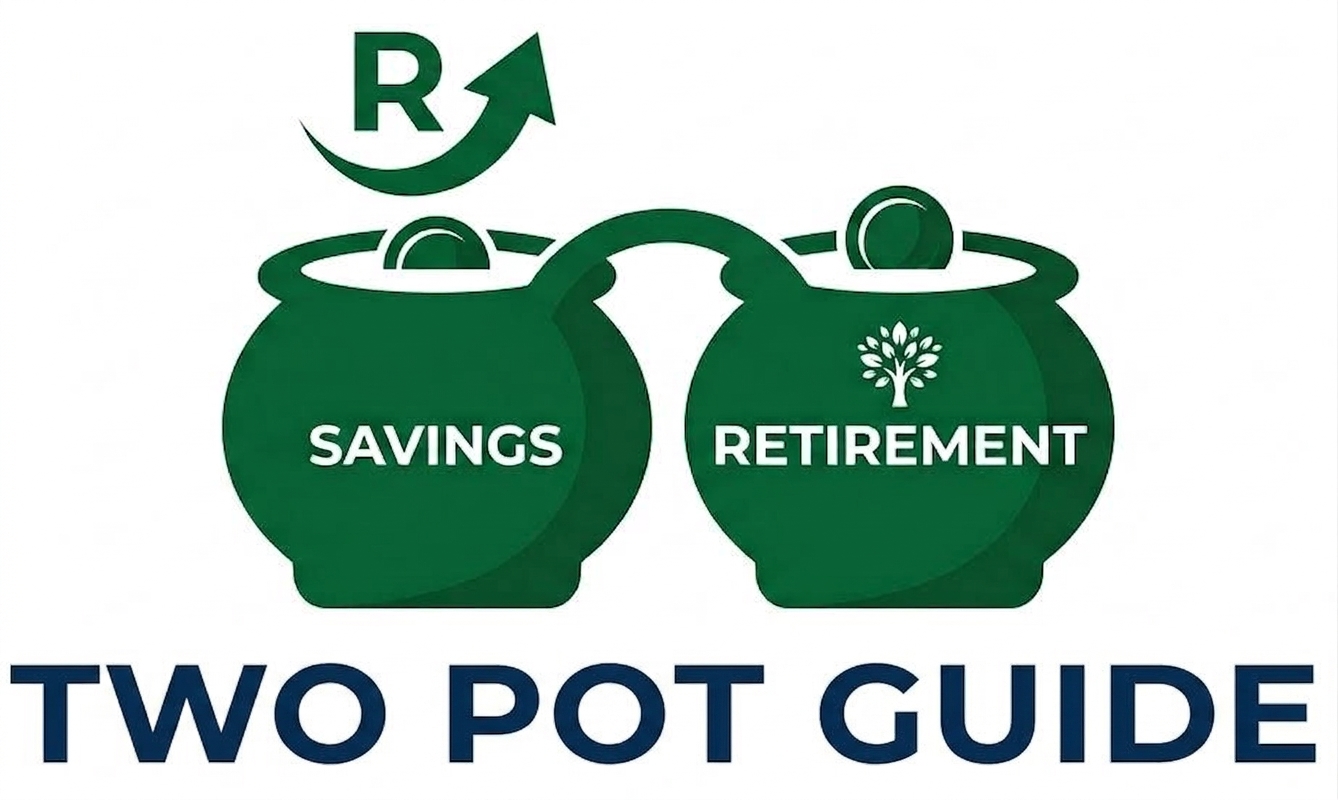
If part of your final payout includes a withdrawal from your retirement fund rather than pure severance pay, the two-pot retirement system introduced in September 2024 changes how that withdrawal works. Under two-pot rules, your retirement savings split into a savings pot, which holds one third of new contributions and can be accessed while you are still working or immediately after retrenchment, and a retirement pot, which holds two thirds and stays locked until formal retirement.
If you are retrenched and choose to access your savings pot, that withdrawal is taxed at your marginal income tax rate, not the more generous lump sum tables that apply to severance and full retirement fund withdrawals. This is a completely different tax treatment from your tax directive for retrenchment covering your severance pay itself, and confusing the two is one of the most expensive mistakes retrenched employees make. Always request a separate SARS tax directive calculation for your savings pot withdrawal before deciding whether to draw it down immediately or leave it invested.
Frequently Asked Questions
How much of my retrenchment package is tax free?
The first R550,000 of your combined lifetime lump sum withdrawals, including severance pay and retirement fund lump sums, is tax free under current SARS rules. Anything above that is taxed on a sliding scale starting at 18 percent.
Who applies for the tax directive for retrenchment, me or my employer?
Your employer applies for the directive through SARS eFiling using an IRP3(a) form, since they are responsible for deducting and paying over the correct tax. You should still confirm with them that this was submitted before your final payslip is processed.
Does the R550,000 tax free threshold reset every time I am retrenched?
No. It is a lifetime cumulative threshold across all your retirement fund lump sums and severance benefits, not a fresh allowance each time you leave a job. If you have used part of it before, only the remaining balance applies to your current payout.
Is notice pay taxed the same way as severance pay?
No. Notice pay and leave pay are taxed as ordinary income at your standard PAYE rate. Only the severance component qualifies for the special lump sum tax tables covered under a tax directive.
Read more: Domestic worker retrenchment package
Ask your employer today for written confirmation of the SARS directive number applied to your severance payout, and request a breakdown showing exactly how much of your final payment falls under severance, notice, and leave pay, since only one of those gets the generous tax treatment. If any part of your payout involves a retirement fund withdrawal, get the separate tax calculation for that before you decide whether to draw it down now or leave it invested. Before you make any final decision about your payout, understanding exactly how the two-pot retirement system affects what you can access immediately versus what stays locked could save you from an unnecessary tax bill.
This article is for informational purposes only and does not constitute legal or financial advice. Labour law and tax rules may change. For advice specific to your situation, consult a registered labour lawyer, a CCMA commissioner, or visit labour.gov.za and sars.gov.za.